There’s nothing quite like that sinking feeling when you spot water pooling where it shouldn’t be — especially in the basement. Maybe you’ve come home after a Melbourne downpour to find damp carpet, bubbling paint, or that unmistakable smell of moisture creeping up the walls. The first question that usually follows isn’t about the mop, it’s: “Is this covered by my home insurance?”
The answer depends on one crucial detail — the cause of the leak. In our 35 years building and restoring homes across Melbourne, we’ve seen every type of basement water issue you can imagine. From sudden pipe bursts under Bentleigh East homes to slow, sneaky seepage through ageing foundations in Bayside, the cause determines whether your insurer will help foot the bill or not.
In this guide, we’ll unpack how insurance companies view basement leaks, what’s typically covered (and what’s not), and which add-on coverages can save you thousands in the long run. We’ll also share a few lessons we’ve learned from local homeowners who found out the hard way that not all water damage is treated equally.
What Homeowners Insurance Typically Covers For A Leaky Basement
Most homeowners are surprised to learn that insurance doesn’t automatically cover every type of water damage. The key phrase to remember is “sudden and accidental.” That’s the line in the sand insurers use to decide whether a leaky basement is a covered event or a homeowner maintenance issue.
In Melbourne, where older properties often rely on clay drainage pipes and decades-old plumbing, it’s not uncommon for water damage to come from internal systems failing unexpectedly. When it does, most standard policies provide cover under the “escape of liquid” clause — as long as the event wasn’t preventable through regular maintenance.
Burst Or Frozen Pipes – When Insurance Pays Up
Even in our relatively mild climate, Melbourne still gets the occasional cold snap that freezes pipes in older or poorly insulated homes. When a pipe bursts, it can release hundreds of litres of water within minutes, flooding the lower levels before you even notice.
In cases like this, insurance typically covers the damage caused by the water, including repairs to floors, plasterboard, skirting boards, and built-in storage. However, most policies won’t cover the cost to replace the damaged pipe itself — that falls under normal wear and tear.
We once helped a homeowner in Oakleigh whose basement flooded after a pipe burst beneath the slab during a cold July morning. The water ruined the carpet and shorted out electrical outlets, but because the event was sudden and accidental, their claim was approved within a week. They were back to normal in under a month — a quick turnaround, provided the damage was properly documented.
Appliance Overflows And Internal System Leaks
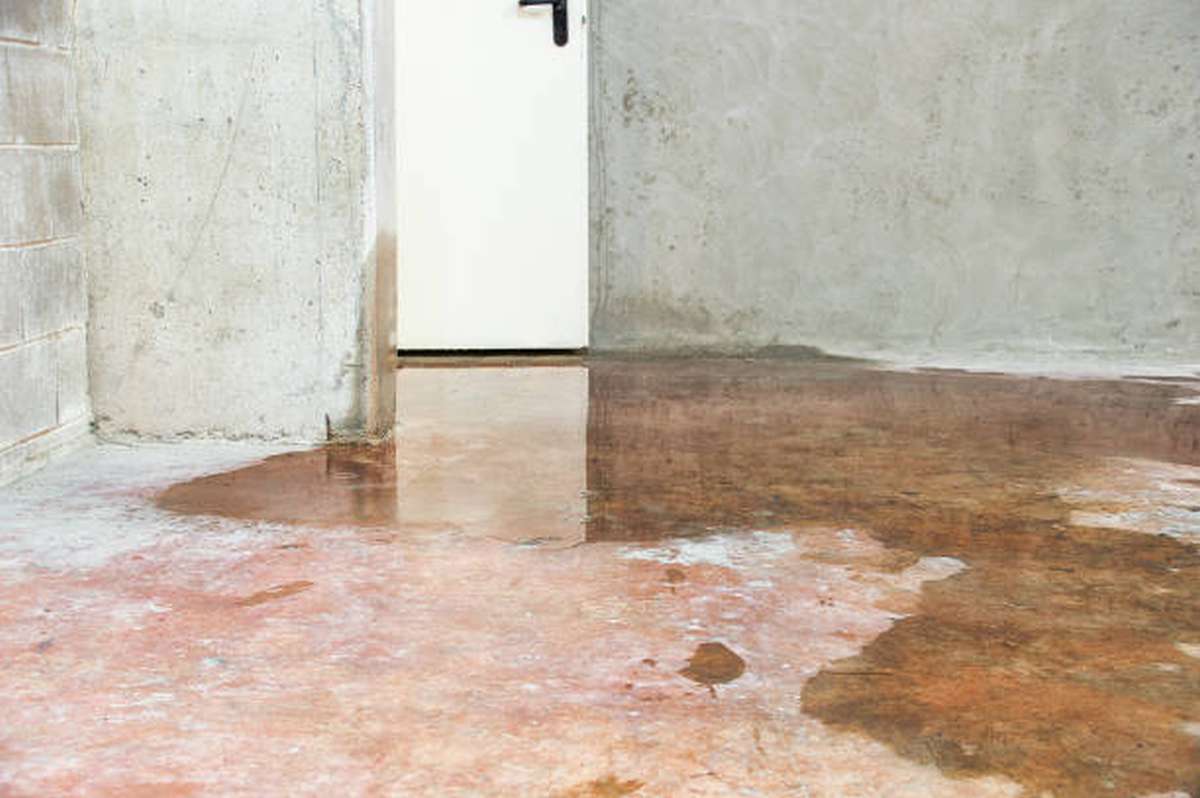
Appliances are another common culprit. A washing machine hose detaching mid-cycle, or a faulty valve on a hot water service, can unleash a steady flow of water straight into the basement. When these internal failures happen suddenly, most policies will pay for the cleanup and repairs.
What’s often overlooked, though, is contents coverage. If you’ve got tools, gym equipment, or stored furniture in the basement, your personal property coverage can help replace them — but only if you’ve included basement storage under your policy. It’s worth reviewing that detail before a leak ever occurs.
At MJS Construction Group, we often see homeowners treating their basements like a forgotten storage shed. We always remind them: if it’s worth keeping, it’s worth covering.
Hvac Or Fire Sprinkler System Discharge
Modern homes and commercial-style builds with heating, cooling, or sprinkler systems carry additional risks. When a valve fails or a sprinkler head cracks, it can discharge water directly into ceiling cavities or down internal walls — and in multi-level homes, that water finds its way straight to the basement.
Under most Australian policies, this type of accidental discharge is covered as long as it wasn’t caused by neglect or faulty installation. It’s another reason why routine servicing by licensed professionals isn’t just good maintenance — it’s also your best defence in an insurance claim.
Example Claim Scenario – The Sudden Leak That Qualified
Not long ago, a Bentleigh East homeowner called after discovering ankle-deep water in their basement on a Sunday morning. Their hot water system had burst overnight, sending hundreds of litres cascading through the space. They did three things right:
- Shut off the water supply immediately.
- Took photos and videos before starting cleanup.
- Called a licensed plumber to document the failure.
When their insurer reviewed the evidence, the claim was approved under the “sudden escape of liquid” clause. They received full coverage for structural repairs and part replacement of flooring and stored items.
It’s a textbook example of how acting fast — and keeping good records — can make all the difference when you’re standing in a pool of bad luck.
When Homeowners Insurance Does Not Cover Basement Leaks
Many homeowners assume that “water damage” means automatic coverage — but in reality, most basement leaks fall into the excluded category. Standard home insurance policies are designed for sudden, accidental events, not gradual or external issues.
Over the years, we’ve seen claims denied simply because the insurer traced the water back to groundwater pressure or poor maintenance — both common in Melbourne’s older homes. It’s tough news for homeowners who discover too late that not all leaks are treated equally.
Flooding And Groundwater Seepage Are Excluded
Flooding is one of the biggest misunderstandings when it comes to home insurance. In plain terms, flooding is water coming from outside — and that means it’s excluded from standard policies. Whether the water entered through a cracked wall, a window well, or seeped up through the slab, if it came from outside, your insurer will classify it as a flood or groundwater issue.
After that wild Bayside storm a few years back, we saw several clients with basements that turned into wading pools. One homeowner in Sandringham had rainwater push through a hairline crack in their foundation wall. The insurer’s assessor classified it as groundwater seepage — not covered. They later took out flood insurance to make sure they’d never face that bill again.
To make this clear, here’s a quick comparison of what’s considered covered versus excluded:
|
Type of Damage |
Source |
Covered by Standard Policy? |
|
Burst pipe under floor |
Internal plumbing |
Yes |
|
Groundwater seepage through foundation |
External source |
No |
|
River overflow or flash flood |
Natural event |
No |
|
Washing machine overflow |
Internal appliance |
Yes |
To protect your property from these external water risks, you’ll need a separate flood insurance policy, available through private insurers or, in some cases, via national programs.
Keep in mind: flood policies often cover only structural elements and essential systems — not personal items stored in your basement. That’s an unpleasant surprise for many after the fact.
Gradual Damage And Lack Of Maintenance
Homeowners insurance isn’t designed to be a maintenance plan. If the damage develops slowly — over weeks, months, or even years — it’s unlikely to be covered.
This includes:
- Slow leaks from old pipes or seals that weren’t repaired promptly.
- Foundation cracks that were left untreated.
- Blocked drains or gutters causing overflow near foundation walls.
- Mould or rot developing from persistent dampness.
We worked with a family in Glen Iris who discovered damp plaster and a musty smell in their basement laundry. After investigation, the assessor found an old pipe joint leaking behind the wall for months. Because it wasn’t sudden or accidental, their claim was denied. The fix cost nearly $9,000 — an expensive reminder that prevention is cheaper than the cure.
Here’s a tip we often share: treat early warning signs like bubbling paint, musty odours, or small cracks seriously. A few hundred dollars spent on maintenance can save tens of thousands in rejected claims.
Sewer Backup And Sump Pump Failures
If water enters your basement through a drain, sewer, or failed sump pump, standard insurance won’t cover it. These events are considered preventable system failures, and you’ll need an add-on policy called Water Backup and Sump Overflow coverage.
It’s not common knowledge, but we’ve seen a rising number of these incidents in Melbourne’s newer subdivisions. As infill developments increase, the stormwater systems are under greater strain. A single backflow during a heavy rain can send water gushing into a basement floor drain. Without the right endorsement, the homeowner is left footing the bill.
To protect against this, check if your insurer offers a water backup endorsement. It’s an optional extra, but one we often recommend — especially in low-lying suburbs or properties built on reclaimed land.
Example Claim Denial – The Slow Leak That Wasn’t Covered
A homeowner in Bentleigh East noticed water marks near their basement stairs — nothing major, just a faint discolouration. They assumed it was condensation and ignored it. Months later, they found mould behind the wall and a slow leak from a pipe fitting.
When they filed a claim, the insurer’s report concluded that the leak had been ongoing for over 30 days — exceeding the allowable timeframe for coverage. The claim was denied on grounds of gradual damage and lack of maintenance.
In the end, they paid for the repairs out of pocket and later invested in a smart leak detection system — a small device that shuts off the water automatically when it senses moisture. A simple preventative step that could’ve saved them thousands.
Optional Add-On Coverages That Protect Against Basement Water Damage
Even the most diligent homeowner can’t prevent every water-related issue. Melbourne’s climate, with its heavy autumn rains and unpredictable summer storms, makes basement leaks a recurring headache — especially for properties built before the early 2000s. The good news? Several optional policy add-ons can fill the gaps left by standard insurance.
Over the years, we’ve seen clients who added just one or two of these endorsements avoid massive out-of-pocket repair bills. The trick is knowing which ones make sense for your home’s layout, age, and local conditions.
Water Backup And Sump Overflow Endorsement
If your home has a basement, sump pump, or floor drains, this one’s worth serious consideration. A Water Backup and Sump Overflow endorsement covers damage when water backs up through drains or overflows from a sump system.
Without this coverage, insurers classify these events as preventable and exclude them from standard policies. But with the endorsement in place, you’re covered for cleanup, repairs, and even some personal property losses caused by the backup.
In one project we handled in Brighton, a heavy downpour overwhelmed the stormwater system, and the homeowner’s sump pump failed mid-cycle. The result: 50mm of standing water across their basement floor. Because they had this add-on, the insurer covered over $12,000 in repairs and restoration — a lifesaver after what could’ve been a major financial setback.
When it’s worth adding:
- Homes with basements below street level.
- Properties relying on sump pumps or gravity-fed drains.
- Homes in areas with older council drainage infrastructure (common in Glen Eira and Bayside).
Flood Insurance
For water that originates outside the home, flood insurance is your only safety net. It covers damage from rising waters due to storms, overflowing rivers, or flash flooding.
However, homeowners often overlook a crucial limitation — flood insurance doesn’t cover everything below ground. In most policies, coverage in basements is limited to essential structural components (foundation, walls, electrical systems, furnace, hot water unit). Contents stored below ground — like gym equipment or furniture — are usually excluded.
Take the case of a Hampton homeowner whose basement flooded after an intense January storm. The external drainage couldn’t keep up, and rainwater entered through a small window well. Thanks to their separate flood insurance policy, structural repairs and replacement of the water heater were covered, but personal items stored downstairs were not.
When it’s worth adding:
- Homes near creeks, coastal zones, or low-lying land.
- Properties with poor stormwater runoff.
- Areas known for heavy rainfall events (southeast suburbs near Dandenong Ranges).
Limited Seepage Or Hidden Leak Coverage (Where Available)
Some insurers offer hidden or gradual leak coverage — a relatively new feature that extends protection to slow leaks that go unnoticed for more than 14 days. It’s not common, but a handful of Australian providers include it for an additional premium.
This type of coverage can be a game-changer in older Melbourne homes where small, undetected leaks can cause big headaches over time. For example, a slow trickle from a corroded pipe joint under a concrete slab might go unnoticed until the smell of dampness sets in. Without hidden leak coverage, that repair could cost thousands. With it, the insurer may cover structural repairs and part of the plumbing work.
When it’s worth adding:
- Homes with concealed plumbing lines under slabs or behind brick walls.
- Properties with finished basements where leaks can go unnoticed.
Quick Comparison Table
|
Coverage Type |
Protects Against |
Included in Standard Policy? |
Ideal For |
|
Water Backup & Sump Overflow |
Drain or sewer backup, sump pump failure |
No |
Homes with basements or floor drains |
|
Flood Insurance |
External flooding from rain or stormwater |
No |
Homes in low-lying or coastal areas |
|
Hidden/Gradual Leak Coverage |
Leaks lasting over 14 days |
Limited availability |
Older homes with concealed plumbing |
Even if your property hasn’t had a leak before, these add-ons can serve as cheap peace of mind. In the insurance world, it’s the quiet months that make the premiums worthwhile.
What To Do If You Discover Water In Your Basement
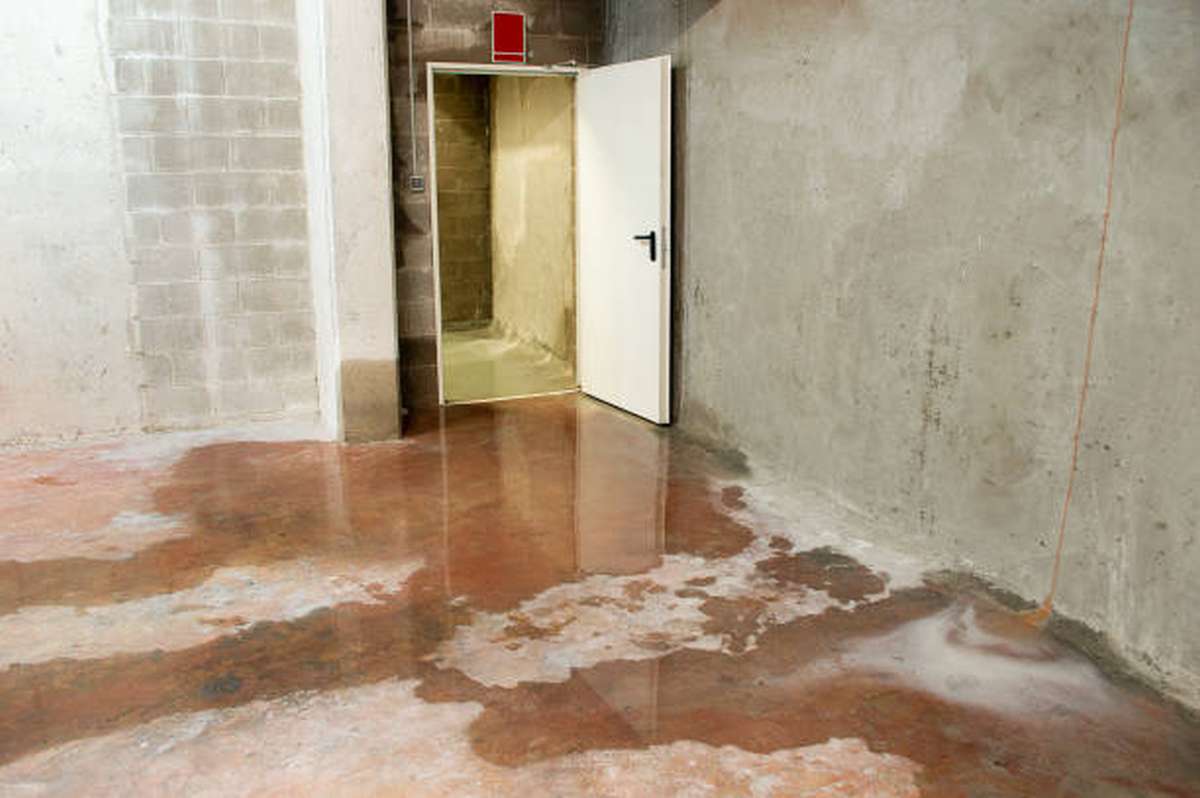
Finding water in your basement can stop you in your tracks. It’s easy to panic, but how you act in those first few hours can make or break your insurance claim — and often determine how costly the repair will be. Over the years, I’ve walked through dozens of flooded basements with homeowners across Melbourne. The ones who fared best were those who acted quickly, documented everything, and called the right professionals early.
Here’s a practical, step-by-step guide that we recommend to every client facing this situation.
Act Immediately To Minimise Damage
Time is the enemy when water is involved. Even a small leak can start damaging plaster, flooring, and electrical fittings within hours.
Follow this checklist as soon as you spot the problem:
- Shut off the water supply. If the source is internal (like a burst pipe or leaking appliance), turn off the main valve immediately.
- Switch off electricity to the affected area. Water and power don’t mix — always err on the side of caution.
- Move belongings to higher ground. Lift furniture, boxes, or tools off the floor to prevent further damage.
- Mop up or extract standing water. Use towels, a wet vacuum, or call in a water restoration company if the water level is significant.
- Ventilate the space. Fans, dehumidifiers, and open windows help reduce moisture and mould growth.
In 2023, we helped a couple in Elsternwick who caught a burst pipe early on a Sunday morning. They cut power, isolated the water, and started drying the space before calling us. Their insurer praised their quick response — it reduced the damage by almost half compared to a similar case the week before, where the homeowner waited overnight.
Document Everything For Insurance
Insurers rely heavily on evidence when assessing water damage claims. The more proof you have, the smoother the process will be.
What to document:
- Take photos and videos of the affected area from multiple angles.
- Record the source of the leak (if visible).
- Keep receipts for emergency repairs or plumber callouts.
- Note dates and times — when you discovered the leak and when each action was taken.
- Save emails or messages from professionals involved in the inspection.
If the damage is extensive, don’t start major repairs until your insurer gives approval. Temporary measures, like drying and cleaning, are fine — but avoid removing walls or flooring before they’ve inspected the site.
Insurers in Victoria typically expect notification within 48 hours of discovery for a valid claim. Miss that window, and you risk losing eligibility.
Seek Expert Assessment For Foundation Or Structural Leaks
If you notice cracks in your basement walls or floor, or water seems to be entering from the ground, it’s best to call a licensed builder or structural engineer. These leaks often point to foundation movement — something we see regularly across Melbourne’s clay-heavy suburbs like Bentleigh East, Glen Iris, and Malvern East.
Our clay soils expand and contract with moisture changes. After a dry spell, they shrink, and then after a week of solid rain, they swell — putting pressure on the foundations. Over time, this movement can open small cracks that let water in during storms.
At MJS Construction Group, we’ve repaired several basements where these soil cycles caused recurring leaks. The repair process often involves crack injection, waterproof membranes, and improved drainage — all of which must meet VBA and Building Code of Australia standards.
If the leak appears structural, contact your insurer and a professional immediately. Early detection could mean the difference between a minor crack repair and a full foundation rectification.
Prevention Checklist
A bit of foresight goes a long way in avoiding future leaks. Here’s a maintenance list every Melbourne homeowner should run through at least once a year — ideally before the storm season (March–May):
|
Maintenance Task |
Recommended Frequency |
Why It Matters |
|
Seal visible foundation cracks |
Annually |
Prevents groundwater entry through weak points |
|
Clean gutters and downpipes |
Twice yearly |
Stops overflow near basement walls |
|
Test sump pump or drainage system |
Quarterly |
Ensures water is pumped away during heavy rain |
|
Check grading around your home |
Annually |
Keeps surface water flowing away from the foundation |
|
Store valuables on shelving |
Ongoing |
Reduces loss from any unexpected leak |
We often say, “The best insurance is a dry basement.” A few hours of maintenance each year can save months of disruption later.
Understanding “Covered Perils” And Claim Triggers
When it comes to water damage, your insurer isn’t just asking what happened — they’re asking how and why it happened. This is where “covered perils” and “claim triggers” come into play.
A covered peril is an event your insurance policy agrees to protect you against. In the case of a leaky basement, this often boils down to whether the water intrusion was sudden and accidental, or gradual and preventable. That single distinction can mean the difference between a full payout and a denied claim.
Over the years, I’ve seen both outcomes — sometimes on the same street. The cause is always the key, not the amount of water or the extent of damage.
The Importance Of The “Sudden And Accidental” Clause
Most Australian home insurance policies include the phrase “sudden and accidental escape of liquid.” This is the foundation of your water damage protection. It means the damage must occur abruptly and unexpectedly — not from something that worsened slowly over time.
Here’s a simple way to think of it:
- Covered: A pipe bursts overnight, flooding your basement.
- Not covered: A pipe has been dripping behind the wall for months, and the plaster finally caves in.
We handled both scenarios for two different homeowners in Bentleigh. One had a pipe rupture from water pressure after a winter freeze — covered in full. The other had an old copper fitting corroding for months — claim denied for “gradual deterioration.” Both had wet floors; only one had an approved claim.
When in doubt, remember this rule: If it happens fast and by surprise, it’s probably covered.
Link Between Policy Language And Claim Outcome
Insurance policies are notorious for fine print, but understanding a few key terms can help you interpret your coverage before trouble strikes.
Here’s a quick breakdown of common terms you’ll find in most Australian home insurance policies:
|
Policy Term |
Meaning |
Typical Coverage Outcome |
|
Escape of Liquid |
Water escaping from a fixed pipe, appliance, or system |
Covered (if sudden) |
|
Flood |
Water entering from outside due to natural causes |
Excluded unless you have flood insurance |
|
Groundwater Seepage |
Moisture entering through soil or foundation |
Excluded |
|
Gradual Deterioration |
Damage occurring slowly or from neglect |
Excluded |
|
Water Backup |
Overflow from drains or sewers |
Excluded unless add-on purchased |
It’s worth reading your Product Disclosure Statement (PDS) once a year — especially if you’ve renovated, added a basement level, or changed your drainage setup. A five-minute skim now can save you a very expensive surprise later.
How Insurers Determine Fault
When you lodge a claim, your insurer sends out a loss adjuster or assessor to inspect the damage. Their job is to determine:
- Where the water came from.
- Whether the event was sudden or gradual.
- If maintenance issues contributed.
They’ll rely on professional reports — often from plumbers, builders, or engineers — along with moisture readings, photographs, and sometimes even CCTV drain inspections.
In one assessment we assisted with in Caulfield, the insurer initially suspected poor maintenance. However, our plumbing report showed a burst connection in a concealed line that failed suddenly. That evidence turned a potential denial into an approved claim.
If you’re ever unsure, get your own licensed builder or plumber to provide a written assessment. Independent documentation can be your strongest ally in proving that the leak was a covered event.
A leaky basement isn’t just a nuisance — it’s a test of how well your home is protected, both physically and financially. Homeowners insurance covers sudden and accidental internal leaks like burst pipes or appliance failures, but excludes gradual damage, external flooding, and poor maintenance. Optional add-ons, like flood or water backup coverage, can close those gaps and save thousands down the track.
From our experience building and repairing homes across Melbourne, prevention always beats remediation. Regular inspections, good drainage, and quick action at the first sign of moisture not only protect your investment but also strengthen your case if you ever need to file a claim.
In short, the best protection against basement leaks is a mix of vigilance, maintenance, and the right coverage — because once water gets in, it doesn’t wait for paperwork.


